APRLOG / All articles / Four airdrops, reviewed: official figures against real prices
Four airdrops, reviewed: official figures against real prices
While a campaign is running, the annualised figures are everywhere. Once it ends, nobody goes back and works out what people actually received. This is the going-back-and-working-it-out article. Everything comes from Binance's own pages and announcements plus the public market-data endpoint, and every number states how it was derived and which day it was taken from.
The finding: across the four rounds we could verify completely, one BNB earned tokens worth five to thirty-one cents at the payout-day close — roughly 0.011% to 0.047% of the BNB's value at the time. All four kept falling after payout; by the 2026-08-22 close they were down between 26% and 56%.
Why only four rounds
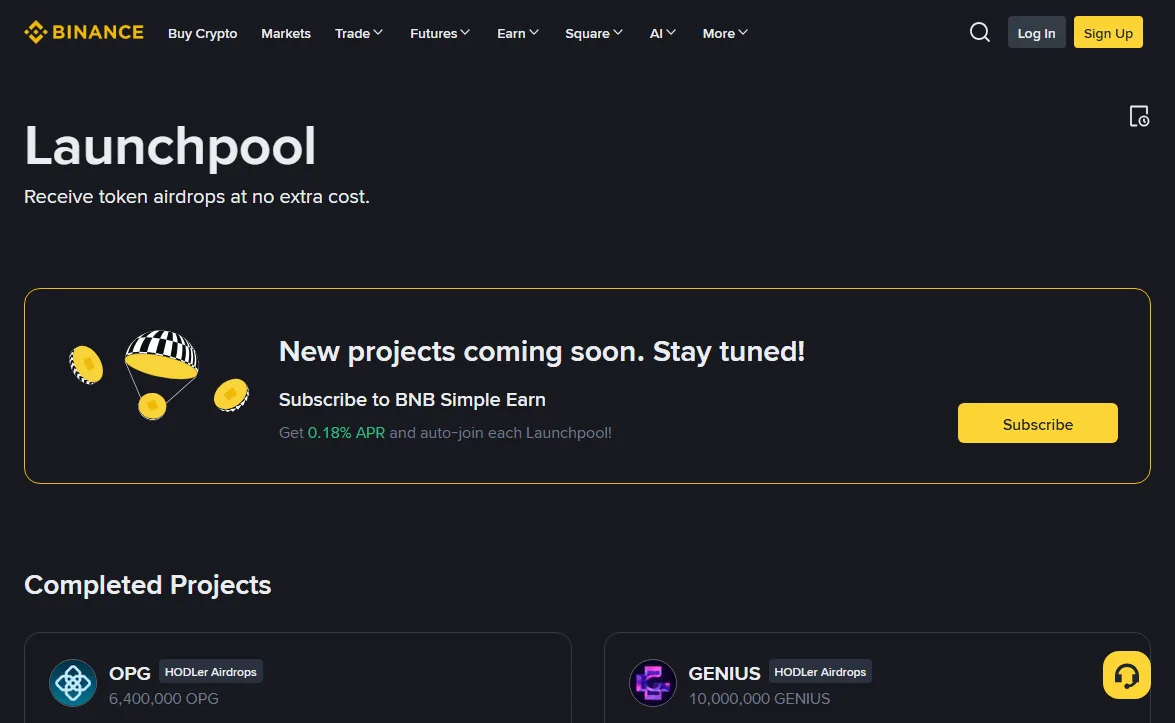
The “Completed Projects” block on Binance's Launchpool page retains, for each round, the total reward and the average airdrop per BNB. When we looked in August 2026, that block held four projects. For earlier rounds the per-BNB field is no longer displayed.
That field is the foundation of this whole review. Without it you would have to estimate pool size and work backwards, and an estimate cannot be written down as a fact. So the rule is simple: if the official figure is gone, the round is not included. Four verified rounds beat eight with half of them guessed.
The basis, stated before the numbers
Where the data comes from
- Total reward and average per BNB — the “Completed Projects” block on the official Binance Launchpool page, verified 2026-08-23.
- Qualifying window and distribution time — each round's official announcement: CHIP, AIGENSYN announcement ID 8c6cfaeddbd04f1595f658ac1dfbd0e7, GENIUS announcement ID 455eedc320bd43e28e2326f58d4aac2a, OPG.
- All prices — daily closes from Binance's public market-data endpoint (USDT pairs, UTC day boundary). Public and reproducible; pull them yourself and check.
What the three pricing bases mean
- First listing day — the close of the token's first daily candle on Binance spot.
- Payout day — the close on the day the official announcement was published. The announcements state distribution completes within hours, so this is the first day you could actually sell.
- 2026-08-22 — the last complete trading day at the time of writing. Using a partial day would not be reproducible.
One basis has to be flagged: “first listing day price”, the figure most reviews of this kind quote, does not apply to HODLer Airdrops. These are retroactive: the snapshot closes, then weeks pass, then the announcement and the credit arrive — and the token has frequently been trading for some time before you receive any. On listing day you did not hold the token and could not sell it. We keep the column so you can reconcile against what you read elsewhere, but the payout-day basis is the meaningful one.
Converting to dollars per BNB
dollars per BNB = average tokens per BNB × the close on that basis
Dividing that by the average BNB close across the qualifying window gives the share of BNB value. The BNB average is the arithmetic mean of the daily closes across those days.
The four rounds
| Project / token | Qualifying window (UTC) | Announced & paid | Official total | Average per BNB |
|---|---|---|---|---|
| USD.AI CHIP | 2026-04-13 –04-15 | 2026-04-28 | 25,000,000 | 1.6988 |
| Gensyn AIGENSYN | 2026-05-04 –05-06 | 2026-05-21 | 100,000,000 | 6.8358 |
| Genius Terminal GENIUS | 2026-05-11 –05-13 | 2026-05-29 | 10,000,000 | 0.6845 |
| OpenGradient OPG | 2026-06-22 –06-24 | 2026-06-30 | 6,400,000 | 0.4923 |
The published side. Totals and per-BNB averages from the Binance Launchpool page; windows and distribution dates from each round's announcement. All verified 2026-08-23.
Now the same quantities against real prices.
| Token | Listing-day close | $ per BNB |
Payout-day close | $ per BNB |
2026-08-22 close | $ per BNB |
Payout to now |
|---|---|---|---|---|---|---|---|
| CHIP | 0.06132 | 0.1042 | 0.06894 | 0.1171 | 0.03020 | 0.0513 | −56.2% |
| AIGENSYN | 0.03993 | 0.2730 | 0.03096 | 0.2116 | 0.02046 | 0.1399 | −33.9% |
| GENIUS | 0.62510 | 0.4279 | 0.45400 | 0.3108 | 0.33390 | 0.2286 | −26.4% |
| OPG | 0.21800 | 0.1073 | 0.13090 | 0.0644 | 0.09640 | 0.0475 | −26.2% |
Prices in USDT, daily closes on a UTC boundary. Dollars per BNB = average per BNB × that column's close. Listing dates: CHIP 2026-04-21, AIGENSYN 2026-05-14, GENIUS and OPG both 2026-05-22.
OPG needs a note. It listed on 2026-05-22, while this round's qualifying window ran 22–24 June with payout on 30 June — the token had been trading for over a month before this distribution. The listing-day column does not apply to OPG at all; it is present only to keep the table shape consistent, and should not be read into.
As a share of the BNB you held
| Token | Average BNB close in the window |
$ per BNB (payout basis) | Share of BNB value |
|---|---|---|---|
| CHIP | 617.02 | 0.1171 | 0.019% |
| AIGENSYN | 633.60 | 0.2116 | 0.033% |
| GENIUS | 669.08 | 0.3108 | 0.047% |
| OPG | 577.63 | 0.0644 | 0.011% |
BNB average is the arithmetic mean of daily closes across the qualifying window. Share = dollars per BNB ÷ that average.
The four together come to roughly 0.11%. That total should not be used the obvious way, for the reason in the next section.
Three things these numbers cannot do
They do not add up to a period return
Binance's page retains four rounds. That does not mean four rounds happened. Other campaigns ran in the same period for which we have no verifiable per-BNB figure, so they are not here. Adding these four gives a lower bound, not a total.
We do not publish an annualised figure
You could take 0.047%, multiply by 365 and divide by 3. The arithmetic works. The action is precisely the one this site keeps warning about: projecting a three-day one-off across a year assumes it repeats identically all year, and it does not. So we do not print it. The reasoning is in the piece on annualised rates.
They do not predict anything
Four rounds is a tiny sample concentrated in one particular stretch of 2026. It supports “these four rounds came out at this magnitude” and nothing beyond that.
What the four rounds do show
One: the price kept falling after payout
All four, by between 26% and 56%. That is consistent with how this kind of distribution works: a large share of recipients never wanted the token, so the distribution itself manufactures continuing sell pressure. It is a property of the format, not of these four projects.
Operationally that means “hold and see” was worse than “deal with it on arrival” in every one of these four. That describes what happened; it does not forecast the next round.
Two: the listing-day price is not a price you can get
Three of the four closed higher on listing day than on payout day (CHIP is the exception). Much of the marketing you will read quotes listing-day or earlier valuations — numbers you never had access to. This is the most immediately useful finding here.
Three: the absolute amounts are small
One BNB earned a few cents to about thirty. Hold ten BNB and a round is worth one to three dollars. That is a long way from what “hold and get free tokens” implies.
It is not worthless — for someone already holding BNB long term, it is income attached to a position they wanted anyway. It is nowhere near a reason to buy BNB: a one per cent move in BNB dwarfs a round's payout. The arithmetic is in the price fell while your coins were locked.
Reproducing this yourself
- Open the completed-projects block on the Binance Launchpool page and copy the total and the average per BNB.
- Search the announcement centre for that project's HODLer Airdrops post; note the qualifying window and the publication time.
- Pull the daily candles for that token's USDT pair from the public market-data endpoint and find the close on each relevant date.
- Multiply the two. That is our “dollars per BNB”.
If your figure differs from ours, the usual causes are the day boundary (UTC or local) and the pair (USDT or something else). If we turn out to be wrong, it goes in the corrections log.
How this page is maintained
It is a snapshot, not a live dashboard. Prices are the 2026-08-22 close and the page will not move with the market. We intend to refresh by hand when a new completed project appears or when prices have moved materially, changing the verification date at the same time.
The same data in sortable form is on the payout review board — the same snapshot, not a second set of numbers.
Ten BNB, in plain money
Percentages are abstract. Suppose someone held 10 BNB in flexible savings across April to June 2026 and did nothing else. Here is what arrived:
| Round | Tokens received | $ at payout | If still held on 08-22 |
|---|---|---|---|
| CHIP | 16.99 | 1.17 | 0.51 |
| AIGENSYN | 68.36 | 2.12 | 1.40 |
| GENIUS | 6.85 | 3.11 | 2.29 |
| OPG | 4.92 | 0.64 | 0.48 |
| Four rounds | — | 7.04 | 4.68 |
Scaled to 10 BNB, in dollars. Token quantity = average per BNB × 10. Same snapshot, different scale.
About seven dollars across four rounds; under $4.70 if never sold. Meanwhile the 10 BNB themselves were worth six to seven thousand dollars. The entire haul from four airdrops is roughly the size of a 0.1% move in BNB — and BNB moves a full percent on an ordinary day.
The comparison is not meant to dismiss the campaigns. For a long-term holder, seven free dollars is seven dollars. It is meant to fix the sense of scale: a by-product of a position you already hold, yes; a reason to change the position, no.
Where the limits of this dataset are
- Four rounds. All that Binance currently retains, not all that happened, and far too few for inference.
- About three months. One market regime; another could look nothing like it.
- Daily closes, not your fills. Real selling involves slippage, fees and your own timing.
- “Average per BNB” is a platform-wide average. Your own allocation depends on your share of qualifying balances and can land either side of it.
- No tax treatment. Receiving an airdrop may be a taxable event in some jurisdictions; entirely out of scope here, see tax on crypto earn income.
Listing the limits is not hedging. A dataset that states its own boundaries is the only kind worth citing.
What we looked at and chose not to publish
So you can see the selection rule in operation, here is what was checked and excluded. Every exclusion has the same cause: no reliable official figure.
Earlier rounds
Binance ran many comparable campaigns before these four. The announcements are still findable and the total rewards are in them, but the average-per-BNB field is no longer displayed on the official page for those rounds.
Without it, computing a per-BNB figure requires knowing total qualifying balances, which has never been published. The only route is estimation, and an estimate cannot be presented as a fact. So those rounds are out.
The advertised APR during the campaign
This is the column we most wanted, because it maps directly onto “marketing versus outcome”. But these are retroactive distributions: the announcements contain no such figure and nothing displayed one while the window ran.
We are not going to compute one and insert it. Manufacturing an “advertised APR” and then using it to argue that advertised APRs are inflated is circular. The column was dropped, and the reason is recorded in the corrections log.
Screenshots of an actual account
The most persuasive evidence would be a real account's credit history. We did not include one, for two reasons: account screenshots expose holdings, and a single account's numbers only reflect that account's share, making them less representative than the platform-wide average Binance publishes.
Other exchanges
This site covers Binance only, because that is where its revenue comes from and cross-platform comparison would not be neutral. That is set out in the affiliate disclosure — if you are comparing exchanges, this is the wrong source.
Keeping this ledger yourself
The review is a table plus persistence. If you want your own, this is the process we actually use.
Record four things when tokens arrive
| Field | Where from | Why record it immediately |
|---|---|---|
| Credit date and time | Account transaction history | Determines which day is the payout price |
| Quantity credited | Account transaction history | Your actual figure, not the platform average |
| Price at the time | Market page or public endpoint | Backfilling later invites the wrong timestamp |
| Announcement link | The announcement centre | Announcements get buried and are hard to find later |
Under a minute at the time; potentially an hour to reconstruct afterwards, and less accurately.
Review quarterly
Take every token credited that quarter, revalue at the current price, and set it beside the value on the day it arrived. You get an answer nobody's marketing can give you: how much of this free money is still there.
After a year of records
A year is enough to answer the deeper question: which is larger, the opportunity cost of maintaining the base position, or the value of what it collected?
If you held the asset anyway, the answer is usually the latter, because the opportunity cost is near zero. If you held it in order to participate, the answer very likely flips. Only your own ledger can settle that; no one else's review substitutes for it.
The field structure in tax on crypto earn income was designed for record-keeping and works for this too.
Why they kept falling after payout
All four falling is the most consistent feature of this dataset. Why? Several explanations are plausible and not mutually exclusive — but all of them are conjecture that this data cannot establish, which is why they sit in their own section.
One: distribution manufactures selling
A large share of recipients did not hold the token out of interest in the project. For them the rational move is converting to something else. Hundreds of thousands of accounts receiving the same token at once produces structural sell pressure independent of project quality.
Two: the payout-day price is itself elevated
Distribution comes with a burst of attention — announcement, notification, discussion, all on one day. That attention supports a bid that fundamentals do not, and it disperses.
Three: the broader market over that period
All four cluster in the first half of 2026. If the wider market was weak, these tokens may simply have followed it, with the airdrop mechanism irrelevant. We have no control group, so this cannot be excluded.
What that means for you
If the first two dominate, “deal with it on arrival” is structurally sensible, because both sell pressure and attention decay are foreseeable. If the third dominates, timing should follow your view of the market rather than the distribution schedule.
We do not know which dominates and will not pretend to. The only established fact is that all four fell. Setting out the candidate explanations lets you judge whether the pattern repeats, rather than having a conclusion handed to you.
This is a record of what already happened. It is not investment advice, it neither guarantees nor predicts any future return, and participation in these campaigns can lose you money. All platform figures are dated snapshots; Binance's own pages and announcements govern.
Common questions
How much does one BNB earn from a single airdrop round?
Across the four rounds reviewed, one BNB earned tokens worth roughly five to thirty-one cents at the payout-day close, or 0.011% to 0.047% of the BNB's value at the time. Rounds differ considerably and none of this implies future amounts.
Why not use the first listing day price?
Because all four are retroactive distributions: the announcement and the credit arrive weeks after the snapshot closes, and the token has often been trading before you receive any. On listing day you held nothing and could not sell at that price. The payout-day close is the meaningful basis.
Did the tokens go up or down afterwards?
All four fell. From the payout-day close to the 2026-08-22 close: CHIP about 56%, AIGENSYN about 34%, GENIUS about 26%, OPG about 26%. That is the record of what happened, not a forecast.
Why only four rounds?
Because Binance's page currently retains the average-per-BNB figure for four rounds only. Without that official number the calculation would rest on an estimate of pool size, and an estimate cannot be published as fact. Rounds we cannot verify are left out.
Are these numbers updated live?
No. This is a hand-checked snapshot with prices at the 2026-08-22 close. The page does not track the market; we refresh it manually and change the verification date when we do.
Can I check these figures myself?
Yes, and we would encourage it. Token quantities come from the completed-projects block on the Binance Launchpool page, windows from each round's announcement, and prices from the public market-data endpoint's daily closes. Multiply and you reproduce every figure in the tables.